United States v. Hemani: Guns, Marijuana, and the Second Amendment

*Tyler Konigsberg

I. Introduction: The Constitutional Challenge to 18 U.S.C. § 922(g)(3) and Its Implications for Marijuana Users.

At a time when marijuana legalization and Second Amendment doctrine increasingly collide, the Supreme Court granted certiorari in United States v. Hemani, positioning the Court to clarify the constitutional limits of firearm prohibitions tied to unlawful drug use.[1] The Fifth Circuit held § 922(g)(3) unconstitutional as applied to a sober person with no history of firearm misuse.[2] The case asks whether 18 U.S.C. § 922(g)(3), which bars firearm possession by anyone “who is an unlawful user of. . . [a] controlled substance[,]” including marijuana, “violates the Second Amendment, as applied to the respondent.[3] The Court will hear the case in March, with a decision likely by early summer.[4]

Continue reading “United States v. Hemani: Guns, Marijuana, and the Second Amendment”
Erosion by ICE: How Immigration Enforcement Undermines the Fair Housing Guarantee

*Sophie Alemi

I. Introduction: Fair Housing Under Attack

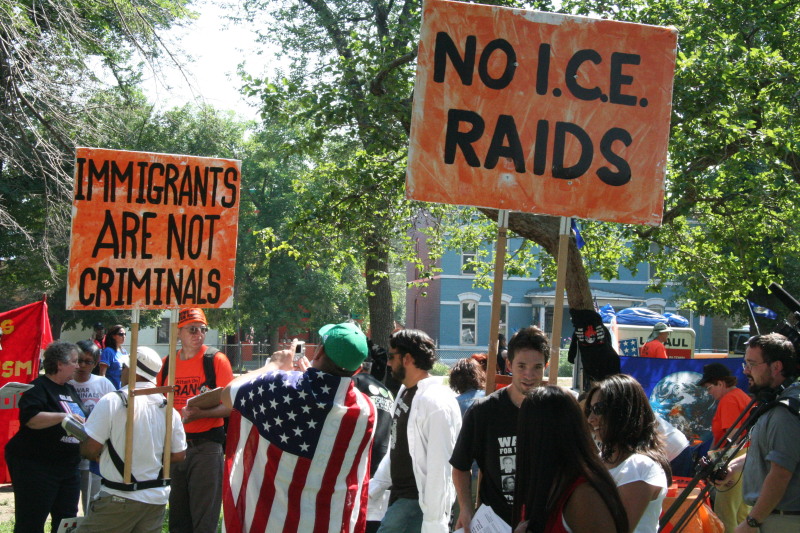
            Under the Trump administration, Immigration and Customs Enforcement (ICE) agents are conducting ongoing raids of schools, workplaces, and residential neighborhoods in major U.S. cities, searching for immigrants to arrest and prosecute.[1] In response to the Trump administration’s deportation agenda, the Department of Homeland Security (DHS) started targeting landlords for their tenants’ “leases, rental applications and identification cards.”[2] Oftentimes, DHS uses subpoenas to intimidate landlords into revealing their tenants’ information; however, there have been multiple reports of such subpoenas being served without a judge’s signature.[3] Even when the subpoenas are unsigned,[4] they contribute to the pressure that DHS is exerting on landlords, which is likely to exacerbate existing discrimination.[5]

Continue reading “Erosion by ICE: How Immigration Enforcement Undermines the Fair Housing Guarantee”

From Inclusion to Exposure: The New Risks of DEI Initiatives in the Workplace Under Title VII

*Macy Hamlett

I. Introduction

In Chislett v. New York City Department of Education, the Court of Appeals for the Second Circuit recently held that mandatory implicit bias training may give rise to race-based hostile work environment claims.[1] With the Second Circuit’s decision strengthening claims, the surge of hostile workplace cases centered around Diversity, Equity, and Inclusion (DEI) initiatives have the potential to survive the summary judgment stage.[2] Chislett represents a shift in the legal framework of race-based hostile work environment claims and DEI.[3] This rapid change stems from the Supreme Court’s June 2025 decision in Ames v. Ohio Department of Youth Services and recent actions from the Equal Employment Opportunity Commission (EEOC).[4] The guidance from the Supreme Court and the EEOC has led to unchartered waters for employers and lower courts.[5]

Continue reading “From Inclusion to Exposure: The New Risks of DEI Initiatives in the Workplace Under Title VII”

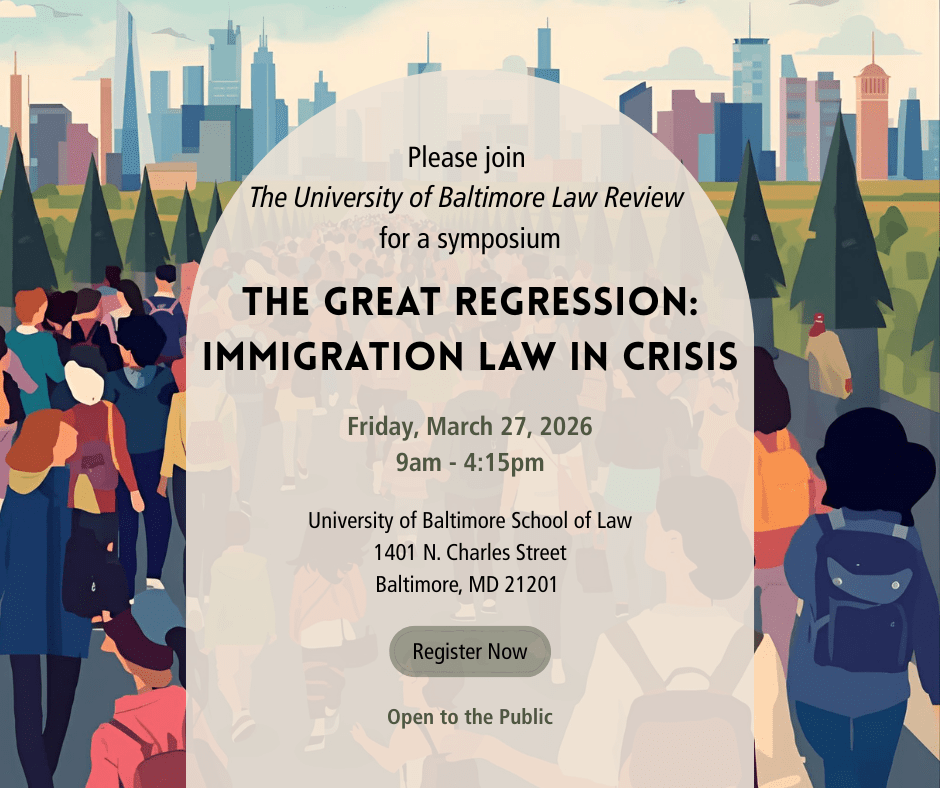
The Great Regression: Immigration Law in Crisis

Title: The Great Regression: Immigration Law in Crisis 

Date and Time: Friday, March 27, 2026, from 9am – 4:15pm

Location: John and Frances Angelos Law Center, 1401 N. Charles St. Baltimore, MD 21201

Click Here to Register 

Continue reading “The Great Regression: Immigration Law in Crisis”

Buy Now, Pay Later, Regulate Never: The CFPB’s Failed Attempt to Govern BNPL Lending

*Colin Livingston

I. Introduction

“Buy now, pay later” programs have quickly become a popular interest-free credit option, with disproportionately high use “among financially vulnerable consumers.”[1] Retailers offer these programs “through payment platforms like Afterpay, Klarna, and Affirm[,]” allowing consumers to pay for “online or in-store purchases. . . [through] installments over a short period” of time.[2] According to a 2025 survey, about one in three U.S. adults has used a “buy now, pay later” service for at least one purchase.[3] Furthermore, the global “buy now, pay later” (BNPL) market is projected “to reach $560.1 billion in 2025. . . [and] expand. . . to approximately $911.8 billion” by the end of 2030, reflecting its rapid growth in how consumers finance and purchase products.[4] Despite the development of this credit option, BNPL programs are not subject to the same regulatory requirements governing traditional credit card companies, including Regulation Z, which implements the Truth in Lending Act.[5]

Continue reading “Buy Now, Pay Later, Regulate Never: The CFPB’s Failed Attempt to Govern BNPL Lending”